BLOGS
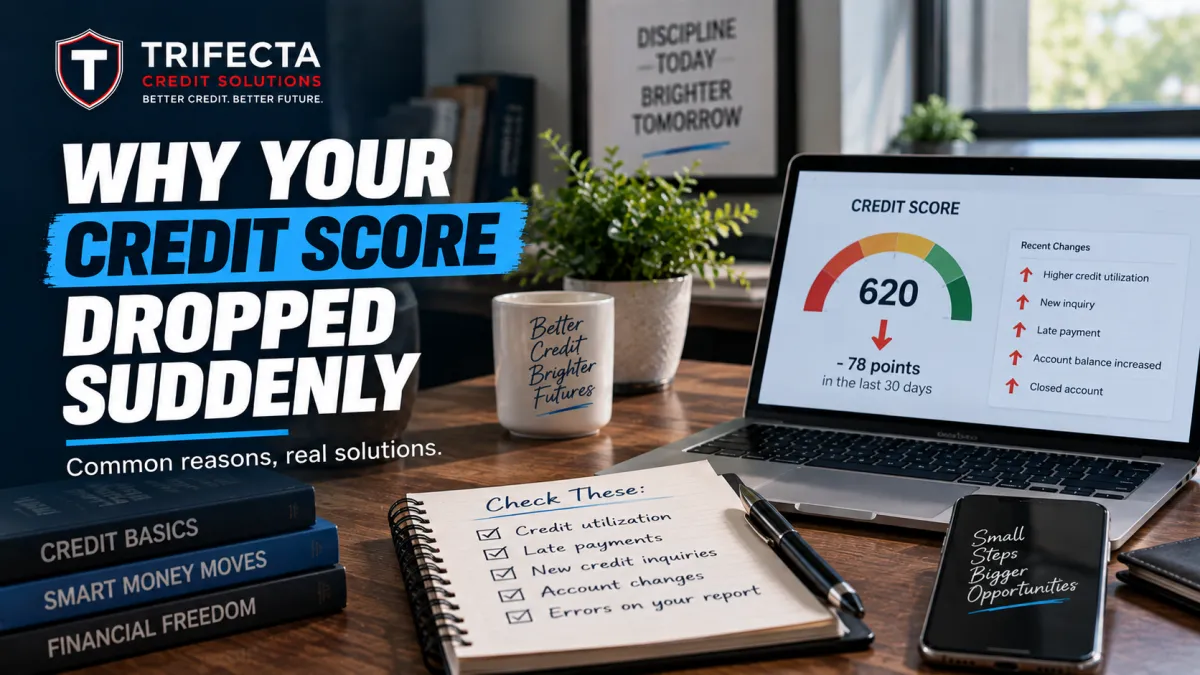
Why Your Credit Score Dropped Suddenly
Why Your Credit Score Dropped Suddenly
You check your credit score and see something you weren't expecting:
It dropped.
Maybe it fell 10 points. Maybe 30. Maybe even more.
And the first question that comes to mind is:
“What did I do?”
A credit score can change when information in your credit report changes. Sometimes the reason is obvious, like a missed payment. Other times, something as simple as a higher reported credit card balance can contribute to the change.
Here are some of the most common reasons your credit score may suddenly drop—and what you should check.
1. Your Credit Card Balance Increased
One of the first things to check is your credit utilization.
Credit utilization compares the amount of revolving credit you're using with your available credit limits.
For example, if you have a $10,000 credit limit and your reported balance increases from $1,000 to $6,000, your utilization jumps from 10% to 60%.
Even if you haven't missed a payment, that higher reported balance may affect your score.
The CFPB notes that using a high percentage of your available credit can negatively affect credit scores. CFPB credit score guidance
2. A Late Payment Was Reported
Payment history is one of the most important components of commonly used credit-scoring models.
If an account becomes sufficiently past due and the lender reports it to the credit bureaus, your score could be affected.
This could happen with:
Credit cards
Auto loans
Mortgages
Student loans
Personal loans
Other reported accounts
Sometimes the culprit is an account you rarely use.
A small recurring charge hits an old card, you don't notice it, and the payment gets missed.
That's why it's important to monitor every open account, not just the cards you use regularly.
3. You Applied for New Credit
Did you recently apply for a:
Credit card?
Auto loan?
Mortgage?
Personal loan?
Other financing?
A lender may perform a hard inquiry when evaluating your application.
Hard inquiries can affect your score, although the impact varies depending on your overall credit profile and scoring model.
One inquiry isn't necessarily a major problem.
But several applications within a short period—particularly for different types of credit—can affect your profile.
4. You Opened a New Account
The inquiry isn't the only change that can happen when you get new credit.
Opening a new account may also affect factors such as the average age of your accounts.
Credit-scoring models consider multiple pieces of information, and adding a brand-new account changes your overall profile.
That doesn't mean opening new credit is always bad.
It simply means you shouldn't open accounts unnecessarily just because you're offered them.
5. You Closed a Credit Card
You paid off a credit card and decided to close it.
That sounds responsible—but it can sometimes have an unintended effect.
Imagine you have:
Card A: $10,000 limit
Card B: $10,000 limit
Total balance: $4,000
Your overall utilization is 20%.
If you close Card B, your available revolving credit falls to $10,000.
If your $4,000 balance remains, your utilization could become 40%.
That's why you should understand the potential impact before closing an account.
6. Your Credit Limit Was Reduced
Sometimes you don't close the account—the card issuer reduces your credit limit.
Suppose you have a:
$10,000 limit + $3,000 balance = 30% utilization
If your issuer reduces your limit to $5,000 while your balance stays the same:
$5,000 limit + $3,000 balance = 60% utilization
You didn't spend another dollar.
But your utilization changed significantly.
If your score unexpectedly falls, check whether any of your credit limits recently changed.
7. A Collection Account Appeared
An unpaid account may eventually be sent to collections and potentially appear on your credit reports.
You might not even realize the debt exists.
Common examples can include:
Old utility bills
Membership accounts
Certain unpaid service bills
Other forgotten obligations
If an unfamiliar collection appears, don't automatically assume it's accurate.
Review the information and determine whether the account actually belongs to you.
8. Negative Information Was Added or Updated
Your credit score is calculated using information contained in your credit reports.
When that information changes, your score can change too.
For example, a creditor may update:
Account balances
Payment status
Credit limits
Account status
Delinquency information
That's why looking only at your score isn't enough.
Look at what changed on the report.
The score is the result.
The report may help you find the reason.
9. An Error Appeared on Your Credit Report
Not every credit-score drop is caused by something you actually did.
Credit reports can contain errors.
Watch for:
Accounts you don't recognize
Incorrect late payments
Wrong balances
Duplicate accounts
Incorrect account status
Outdated information
If you identify inaccurate or incomplete information, you have the right to dispute it. The CFPB provides guidance for disputing errors with both credit reporting companies and companies that furnished the information. CFPB credit-report dispute guide
10. You're Looking at a Different Credit Score
Here's another possibility:
Your credit didn't necessarily get worse—you may simply be looking at a different score.
There isn't just one universal credit score.
Different lenders and consumer services may use different:
Credit bureaus
Scoring models
Versions of scoring models
Data update dates
So the score you see in one app might differ from the score shown somewhere else.
Compare apples to apples before assuming your score suddenly crashed.
What Should You Do After a Sudden Credit Score Drop?
Don't panic and start opening or closing accounts randomly.
Instead, investigate.
Start by:
Reviewing your credit reports.
Checking recently reported balances.
Looking for late payments.
Reviewing new inquiries and accounts.
Checking whether credit limits changed.
Looking for unfamiliar collections.
Identifying inaccurate information.
Comparing the same scoring model when possible.
Once you understand why the score changed, you can decide what actually needs attention.
Can Your Credit Score Recover?
Potentially, yes.
A credit score isn't permanently frozen at one number.
As information on your credit reports changes, your score may change as well.
Depending on what caused the decline, strengthening your credit could involve:
Paying bills on time
Reducing revolving balances
Correcting legitimate reporting errors
Avoiding unnecessary applications
Keeping debt manageable
Building positive payment history
How quickly your score changes will depend on your individual credit profile and the scoring model being used.
There is no guaranteed number of points or timeline.
Don't Just Watch Your Score—Watch Your Credit Report
This is the biggest takeaway.
People often obsess over whether their score went up or down five points without looking at the information behind it.
Your credit report tells the story.
Your score summarizes that information.
So when your score suddenly changes, ask:
“What changed on my credit report?”
That's where you'll often find the answer.
Did Your Credit Score Suddenly Drop?
Don't guess about what's hurting your credit.
Trifecta Credit Solutions can help you understand your credit profile, identify potential issues, and develop a strategy for building stronger credit habits.
Whether you're preparing to buy a home, apply for funding, or simply want better credit, understanding what's happening is the first step.
Schedule your FREE credit consultation with Trifecta Credit Solutions today and find out what's really affecting your credit.
Follow Us


Contact Us
4536 Hamilton Blvd.
1st Floor
Allentown PA 18103