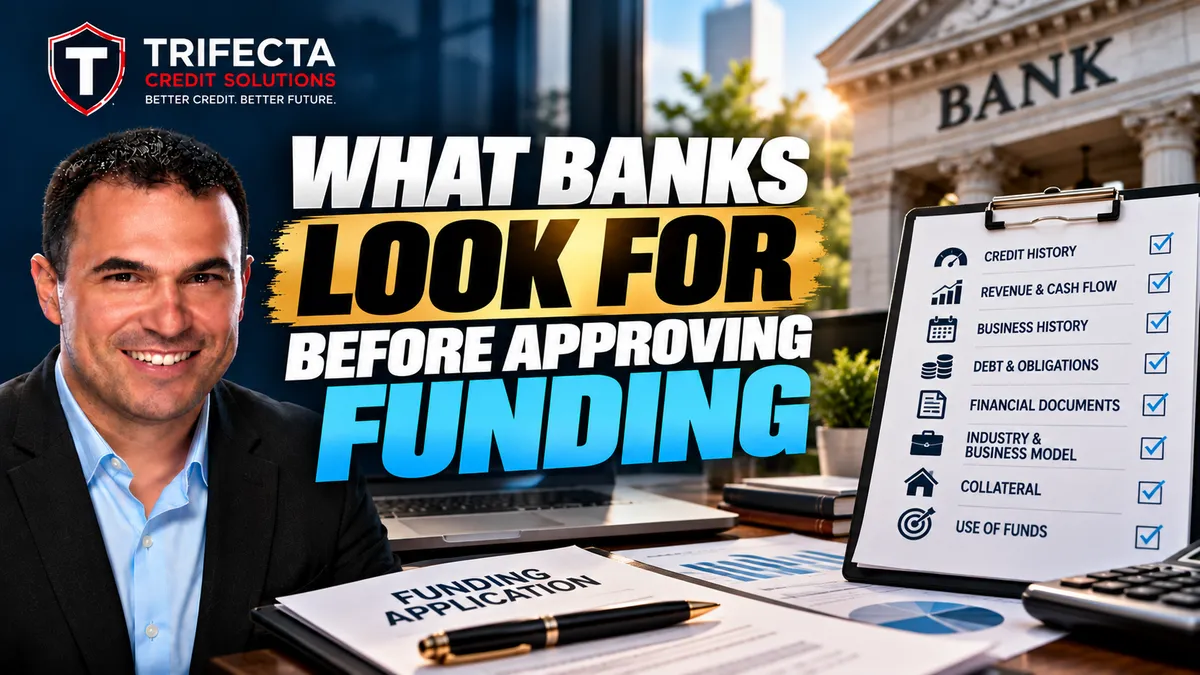
What Banks Look for Before Approving Funding
What Banks Look for Before Approving Funding
Getting approved for business funding isn't just about having a good idea or running a successful company.
Banks want to know one important thing:
Can your business responsibly repay the money it borrows?
You might have steady customers, strong sales, and plans to expand. But if your financial records, credit history, or cash flow don't meet a lender's requirements, getting approved may be difficult.
Understanding what banks evaluate can help you prepare before submitting an application.
Here are the biggest factors that can influence business funding decisions.
1. Your Personal Credit History
Many business owners assume that banks only look at business credit when reviewing a business funding application.
That's not always true.
For smaller businesses, especially newer companies, lenders may review the owner's personal credit history.
They may evaluate:
Payment history
Outstanding debt
Credit utilization
Recent credit inquiries
Collections or charge-offs
Overall credit management
Your personal credit profile can give lenders insight into how you've managed financial obligations.
A stronger personal credit profile may improve your financing options, but it doesn't guarantee approval.
2. Your Business Credit Profile
If your company has established business credit, lenders may also evaluate its borrowing and payment history.
A business credit profile can reflect how your company handles financial obligations with creditors, suppliers, and lenders.
Banks may consider whether your business consistently pays its obligations, has outstanding debts, or has experienced serious payment problems.
Building business credit takes time.
Maintaining accurate company information, using appropriate reporting accounts, and making payments on time can help establish a more reliable financial history.
3. Your Business Revenue
Banks want to understand how much money your business generates.
Revenue helps lenders evaluate the size and activity of your operation.
They may request bank statements, financial statements, or other documentation to verify your business income.
However, high revenue doesn't automatically mean a business is profitable or financially healthy.
A company generating $100,000 in monthly sales may still struggle financially if its expenses consume nearly all that revenue.
That's why banks look beyond sales numbers.
4. Your Cash Flow
Cash flow is one of the most important factors in business financing.
It shows how money moves into and out of your business.
A company may have strong sales but still experience financial pressure because customers pay late, inventory costs are high, or operating expenses are difficult to manage.
Lenders want to understand whether your business generates enough available cash to support its existing obligations and the proposed financing.
Before applying, review your cash flow and ask:
Can my business comfortably afford another payment without putting daily operations at risk?
5. Your Existing Debt
Banks don't only consider how much money your business earns.
They also look at how much it already owes.
Existing business loans, lines of credit, equipment financing, and other financial obligations can affect borrowing capacity.
Some lenders calculate a debt service coverage ratio, or DSCR, to evaluate whether available cash flow can support debt payments.
Different lenders and financing products use different calculations and requirements.
Taking on additional financing without understanding your existing obligations can create unnecessary financial pressure.
6. How Long You've Been in Business
Time in business can influence financing eligibility.
Established businesses often have more financial records available for lenders to review.
A company operating for several years may be able to demonstrate revenue patterns, profitability, and repayment history.
New businesses may have fewer records, making some traditional financing options more difficult to obtain.
However, being a startup doesn't automatically eliminate every financing opportunity.
Available programs and qualification requirements vary.
7. Your Business Bank Statements
Bank statements can reveal important information about a company's financial activity.
Depending on the lender, they may help verify revenue, deposits, cash balances, and account management.
Banks may also examine recurring overdrafts, returned payments, or significant changes in account activity.
Keeping business and personal finances separate makes your records easier to understand.
A dedicated business bank account is an important part of maintaining organized financial records.
8. Your Financial Documents
One common reason business funding applications become delayed is incomplete documentation.
Depending on the financing product, lenders may request:
Business tax returns
Personal tax returns
Profit and loss statements
Balance sheets
Business bank statements
Business formation documents
Ownership information
Existing debt schedules
Financial projections
Not every lender requires every document.
But having accurate, organized records can make the application process smoother.
9. Your Industry and Business Model
Not every business operates the same way.
An auto repair shop has different financial needs from a restaurant, construction company, or consulting business.
Banks may evaluate industry risks, operating expenses, revenue patterns, and the overall stability of the business model.
Some lenders specialize in certain industries, while others restrict particular business activities.
This is why finding a suitable financing product can be just as important as preparing the application itself.
10. Collateral and Personal Guarantees
Some financing products require collateral.
Collateral may include equipment, vehicles, real estate, or other qualifying business assets.
Other financing arrangements may require a personal guarantee from the business owner.
A personal guarantee can make the owner personally responsible for repayment under the agreement's terms.
Before accepting funding, understand what assets or personal obligations may be at risk.
11. How You Plan to Use the Funding
Banks often want to know why your business needs capital.
Are you purchasing equipment?
Expanding operations?
Hiring employees?
Buying inventory?
Managing working capital?
Acquiring another business?
A clear funding purpose helps lenders evaluate whether the financing aligns with your company's operations and financial capacity.
Rather than requesting the largest amount available, determine how much capital you actually need and how it will support your business.
12. Your Overall Financial Stability
Banks generally evaluate the complete financial picture rather than relying on one number.
A business with strong revenue but weak cash flow may face challenges.
A company with excellent credit but insufficient income may also struggle to qualify.
A profitable business with disorganized financial records may experience delays during underwriting.
The strongest preparation involves improving several areas together.
Credit, revenue, cash flow, debt management, and documentation all matter.
Common Reasons Business Funding Applications Get Denied
Business funding applications can be declined for several reasons, including:
Credit history that doesn't meet lender requirements
Insufficient cash flow
Excessive existing debt
Limited time in business
Inconsistent or insufficient revenue
Incomplete financial documents
Industry restrictions
Insufficient collateral when required
Failure to meet a specific program's eligibility standards
A denial doesn't necessarily mean your business will never qualify.
It may mean you need to strengthen your financial profile, adjust the financing amount, or explore a different product.
How to Prepare Before Applying for Business Funding
Preparation can make a meaningful difference.
Start by reviewing your personal and business credit reports.
Make sure your business records are accurate and up to date.
Understand your revenue, expenses, cash flow, and existing debt.
Organize your financial documents.
Separate personal and business transactions.
Most importantly, determine exactly how much financing you need and how your business plans to repay it.
Don't wait until your business urgently needs money to begin preparing.
Funding Approval Starts Before the Application
Many business owners focus on finding funding only when an opportunity or financial challenge appears.
But financing readiness should be part of your long-term business strategy.
The more you understand your company's financial position, the better prepared you'll be to evaluate financing opportunities.
Remember:
Getting approved is important. Getting funding your business can responsibly afford is even more important.
Is Your Business Ready for Funding?
Whether you're planning to expand, purchase equipment, increase inventory, or improve working capital, understanding your credit and financial profile is a valuable first step.
At Trifecta Credit Solutions, we help business owners better understand their credit profiles, identify potential areas for improvement, and prepare for future financing opportunities.
Call 844-342-6669 to schedule your FREE consultation today.
Visit https://trifectacreditsolutions.com
Better Credit. Better Future.

