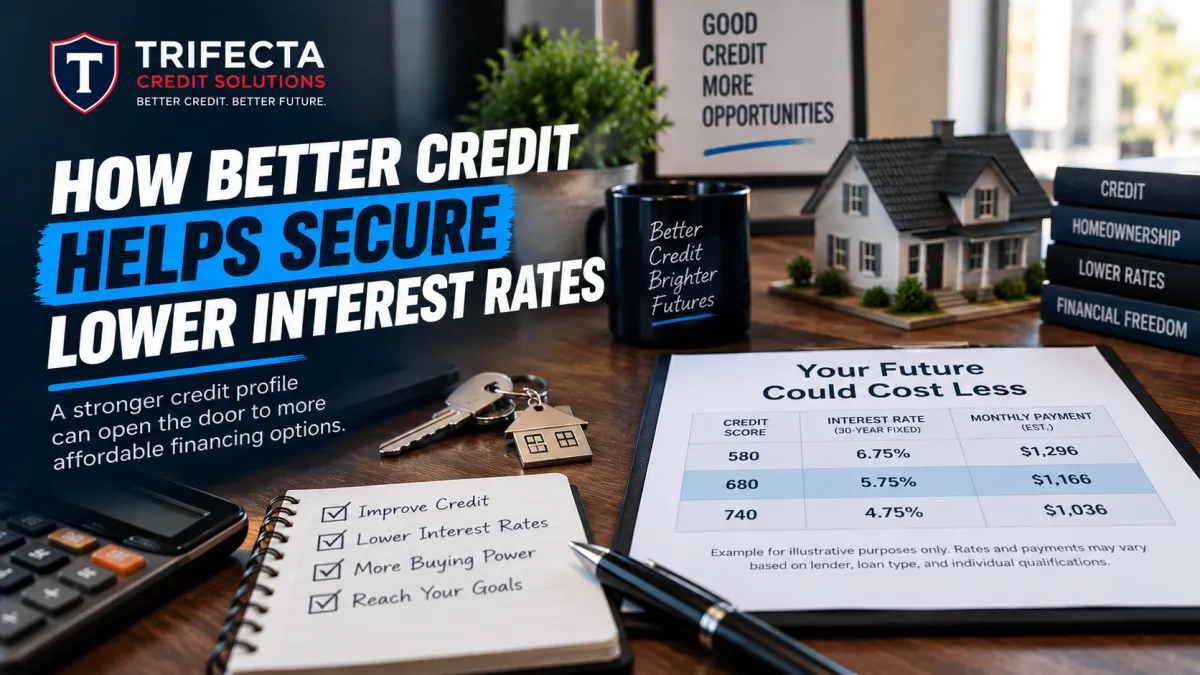
How Better Credit Helps Secure Lower Interest Rates
How Better Credit Helps Secure Lower Interest Rates
When most people think about improving their credit, they focus on one goal:
Getting approved.
But approval is only part of the picture.
Your credit profile can also influence the interest rates and financing terms you're offered. A stronger credit profile may help you qualify for more competitive rates, potentially reducing how much you pay over the life of a loan.
That can matter whether you're financing a home, purchasing a vehicle, applying for a personal loan, or pursuing other financing opportunities.
Here's why better credit can potentially mean lower borrowing costs—and what you can do to strengthen your credit before applying.
Why Does Your Credit Affect Your Interest Rate?
When a lender gives you money, they're taking a risk that you'll repay it according to the agreement.
Your credit history helps lenders evaluate that risk.
A history of responsible borrowing may suggest that you've consistently managed credit obligations successfully.
On the other hand, a credit profile containing missed payments, high balances, collections, or other problems may indicate greater lending risk.
When lenders perceive greater risk, they may compensate by offering a higher interest rate—or they may decline the application altogether.
This is why your credit can influence both whether you qualify and what borrowing may cost you.
Better Credit Can Mean More Competitive Loan Offers
A stronger credit profile may give you access to more financing options.
Depending on the lender and loan product, better credit could potentially help you receive:
Lower interest rates
Better loan terms
More competitive financing offers
Higher approval odds
Lower borrowing costs
Greater financial flexibility
However, your credit score isn't the only factor lenders consider.
Income, debt, loan amount, down payment, collateral, market conditions, and the type of financing can also influence the rate you're offered.
Small Interest Rate Differences Can Add Up
A difference of one or two percentage points might not sound significant.
But when you're borrowing thousands—or hundreds of thousands—of dollars, that difference can become substantial over time.
Consider a long-term mortgage.
Even a relatively small difference in the interest rate can change your monthly payment and the total interest paid over the life of the loan.
The same principle can apply to auto loans, personal loans, and other financing.
That's why improving your credit before borrowing isn't just about seeing a higher number on your credit app.
It can potentially have real financial value.
How Credit Scores Influence Mortgage Rates
Your credit can be especially important when purchasing a home.
Mortgage lenders evaluate multiple factors when determining eligibility and pricing, and credit is one of them.
A stronger credit profile may help you access more competitive mortgage options, while weaker credit could result in higher rates or fewer available choices.
If homeownership is one of your goals, preparing your credit several months before applying can give you time to address potential problems.
How Credit Can Affect Auto Financing
The price of the vehicle isn't the only number that matters when buying a car.
Your interest rate can significantly influence what you ultimately pay.
Two people could finance the same vehicle for the same amount but receive different rates because their financial and credit profiles are different.
The borrower receiving the lower rate may ultimately pay significantly less for the vehicle.
Before visiting the dealership, understanding and improving your credit can help you approach financing from a stronger position.
What Can You Do to Improve Your Credit Before Borrowing?
If you know you'll need financing in the future, preparation can help.
Here are several areas to focus on.
1. Pay Your Bills on Time
Payment history is one of the most influential factors in commonly used credit-scoring models.
Consistently paying your accounts on time helps establish a history of responsible credit management.
Consider using:
Automatic payments
Calendar reminders
Banking alerts
Account notifications
Protecting your payment history should be a priority when you're working toward stronger credit.
2. Lower Your Credit Card Balances
High revolving balances can affect your credit utilization.
Credit utilization measures how much of your available revolving credit you're currently using.
For example, if your credit card has a $10,000 limit and you're carrying a $7,500 reported balance, your utilization on that account is 75%.
Reducing revolving balances can lower your utilization and may help strengthen your credit profile.
Generally, lower utilization is better.
3. Check Your Credit Reports for Errors
Don't assume everything on your credit report is correct.
Review your reports and look for potential issues such as:
Accounts you don't recognize
Incorrect late payments
Incorrect balances
Duplicate accounts
Outdated information
Accounts incorrectly reported as open
Possible identity theft
If you find inaccurate or incomplete information, you have the right to dispute it.
However, accurate negative information generally cannot simply be removed because it's hurting your score.
4. Avoid Applying for Unnecessary Credit
Opening several new accounts in a short period may affect your credit profile.
Applications can result in hard inquiries, while opening new accounts may affect other scoring factors.
If you're preparing for a major purchase such as a home, be especially careful about taking on unnecessary new debt.
Applying strategically is generally better than applying everywhere hoping for an approval.
5. Don't Max Out Your Credit Cards
You might make every payment on time and still experience credit problems if your revolving accounts consistently report high balances.
Using most or all of your available credit can signal greater financial pressure.
Try to keep balances manageable and avoid relying on your entire available limit.
6. Build Positive Credit History Over Time
Strong credit generally isn't built overnight.
Lenders want to see evidence that you can responsibly manage financial obligations over time.
That means:
Paying on time.
Keeping balances manageable.
Avoiding unnecessary debt.
Maintaining healthy accounts.
Correcting legitimate reporting errors.
Consistency matters.
7. Shop With Your Credit in the Best Position Possible
If you're planning a major financial move, don't wait until the day you apply to think about your credit.
Consider preparing several months in advance.
That gives you time to review your reports, reduce balances, correct legitimate errors, and establish stronger financial habits.
The objective is to approach lenders with the strongest profile you reasonably can.
A Lower Rate Can Mean More Than a Lower Payment
Securing a lower interest rate can potentially benefit you in several ways.
You may have:
A lower monthly payment
Less interest paid over time
More room in your monthly budget
Greater flexibility to save or invest
Lower overall borrowing costs
Those savings can become meaningful over several years.
That's why credit improvement shouldn't only be viewed as a way to qualify for financing.
It's also about potentially qualifying for better financing.
Don't Chase a Perfect Credit Score
You don't necessarily need perfect credit to receive competitive financing.
And reaching a particular credit score doesn't guarantee a specific rate.
Different lenders have different underwriting standards, and market interest rates change over time.
Instead of chasing a perfect number, focus on improving your overall credit profile.
A healthy credit profile combined with manageable debt, stable income, and responsible financial habits can put you in a stronger position when it's time to borrow.
Better Credit Can Create Better Financial Opportunities
Credit affects more than what's displayed on a credit-monitoring app.
It can potentially influence the financing options available to you and how much borrowing ultimately costs.
Improving your credit today may help you when you're ready to:
Buy a home
Finance a vehicle
Apply for a personal loan
Access business funding
Refinance existing debt
Pursue other financial opportunities
Small improvements to your financial habits today can potentially produce meaningful savings later.
Want to Improve Your Credit Before Applying for Financing?
Don't wait until after receiving a high-rate offer to start thinking about your credit.
Trifecta Credit Solutions can help you understand your credit profile, identify potential areas for improvement, and develop a strategy for building stronger credit.
The goal isn't simply to get approved.
It's to put yourself in a stronger position to qualify for better financial opportunities.
Schedule your FREE credit consultation with Trifecta Credit Solutions today and start building the credit you deserve.

